Monday, October 12, 2015

Rising Rates. Look closer for opportunities.

After more than six years, the Fed is finally poised to end its zero-interest-rate policy and embark on its first rate hiking cycle in nearly a decade.

We believe this is no ordinary rate cycle – and that the Fed is simply “normalizing” rates from their low levels since the financial crisis. The Fed has also signaled that rate increases will be gradual, which should keep interest rates below historic averages for some time. As a result, we expect rates to rise slowly, remaining below historical averages for some time.

Moreover, we believe that rising rates will be along the strengthening, growing economy – and for well-prepared investors, rising rates can signal opportunity.

A thoughtfully allocated, diversified portfolio can help reduce the impact of rising rates as well as capture growth potential.

1st: Seek a better balance of risk and return

Seek a better balance of risk and return by focusing on credit exposure while reducing interest rate exposure. Corporate bonds typically provide additional yield over Treasuries. Shortening the duration of your bond portfolio can help to reduce your interest rate risk. Combining these actions can be an effective way to navigate a rising rate environment.

Barclays U.S. 1-3 Year Credit Bond Index performance (June 2004 – June 2006)


Source: Barclays as of 8/12/15. Index returns are for illustrative purposes only. Index performance returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index.


_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Monday, October 5, 2015

Is there a recession on the horizon?

The last few days have reminded everyone how quickly markets can turn. In the space of barely a week, the VIX Index, a measure of market volatility, spiked from 13, suggesting extreme complacency, to over 50, evidencing total panic.

Are the fears overblown? Many think so. Some see more to come. What is the reality?

1. The United States is a relatively closed economy

Most U.S. economic activity, nearly 70% of it, comes from domestic consumption. While the country isn’t immune to external shocks, there needs to be a transmission mechanism, such as a spike in oil prices, to impact the domestic economy.

Though a strong dollar and weakness in China have had a negative impact on U.S. corporate earnings, neither has had a material impact on overall U.S. growth. In fact, some of the disruptions from overseas come with silver linings for U.S. consumption and growth: lower rates and cheaper oil.

2. Higher rates are unlikely to derail the recovery

Rates are falling, supporting the housing market. Given low inflation and falling inflation expectations, the Federal Reserve (Fed) is likely, at most, to execute a single rate hike this year. This is in contrast to how most recessions start, with the Fed moving too aggressively and rates rising too rapidly.

3. Cheaper oil is a positive for U.S. consumers

Though the U.S. now has a large domestic energy industry that is feeling the pain from lower oil and the U.S. consumer certainly faces many headwinds, cheaper gasoline should support U.S. consumption.

4. There is little statistical evidence that the U.S. economy is slowing

Prior to the last recession there were several red flags signifying a recession ahead. According to Bloomberg data, leading indicators had been negative for nearly two years, new manufacturing orders slipped into contraction territory in January 2008 and the Chicago Fed National Activity Index (CFNAI), my preferred metric for forecasting near-term activity, had been consistently in negative territory for most of 2007 and all of 2008.

This time around, lower rates and cheaper gasoline help explain why the numbers look very different, as Bloomberg data show. The CFNAI actually hit a 7-month high in July, leading indicators are up roughly 4 percent year-over-year, and despite the slowdown in China, the new orders component of the U.S. ISM survey is 56.5, consistent with solid if uninspiring growth.

There are two caveats. 

First, in today’s slow growth world, it won’t take much to knock the U.S. economy off of its trajectory. As we’ve seen in recent years, a cold winter is enough to cause at least a temporary contraction.

Second, it’s possible to have a bear market without a recession, though I don’t expect this to occur. But if international market volatility becomes severe enough, it could drag down U.S. stocks, even as the U.S. economy continues to grow.

_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Tuesday, September 22, 2015

5 Things Bill Gates and other mega entrepreneurs have in common

Bill Gates' net worth is around $80 billion. He owns the $12.6 billion ownership of Microsoft. He also owns a $4.5 billion ownership in Canadian National Railroads, a $3 billion ownership in Republic Services, and a $2.8 billion ownership in in Ecolab. His diversified investments, through Cascade Investments, amount to $37.6 billion. 

As such, Microsoft, the company he started and associated with the most, stands for only 16% of his family wealth. 

Bill Gates is a mega entrepreneur. 

What sets very successful entrepreneurs, like Bill Bill Gates, apart from the rest? What turns them into mega entrepreneurs running a myriad of companies, overseeing immense and complex web of capital, and forging multigenerational wealth and legacy?

Here are some interesting statistics on mega entrepreneurs:
  • One third of FORTUNE 500 companies are owned or controlled by mega entrepreneurs or their families
  • 67% of NYSE companies are owned or controlled by mega entrepreneurs or their families
On the other hand:
  • About 30% of entrepreneur started and led business survive to the second generation
  • Only 12% make it to the third generation
  • Only 3% make it to the fourth generation
Many wonder what has become of the Rockefellers' ownership and clout over Exxon, Mobil, Chevron, Amoco, Standard Oil of Ohio, Atlantic Richfield, etc. We wonder as well, but its not there...anymore.

All entrepreneurs face the same challenges as they grow their start-ups in to successful companies:
  1. Raising capital without losing control 
  2. Recruiting and retaining top talent 
  3. Business continuation and succession 
  4. Converting profits and value to wealth
How mega entrepreneurs deal and keep dealing with the above challenges makes the difference. 

So, what sets mega entrepreneurs, apart from the rest? 

  1. Mega entrepreneurs have the "big-picture focus".
  2. They take risk and leverage financial and human capital to grow their enterprise.
  3. They rely on their entrepreneur's offices to manage finances, support M&A deals, raise or repay personal capital, execute financial reorganizations or restructure debt. Employees of their core companies are not involved in these processes. 
  4. Liquidity and cash management is given a high priority, managing cash efficiently and having it ready for difficult times and when great opportunities arise.
  5. Risk management is paramount.
Below are some examples of mega entrepreneurs and their strategies. 

Click the graphic to enlarge
Susanne Klatten: Dynasty Company as the Backbone of Dynasty Fortune. Wealth created though growth of a single company, BMW. Company is still a key asset of the family and its business identity. Other key assets are acquired and sold in line with “Dynasty Company” strategy

Click the graphic to enlarge
Leonardo Del Vecchio: Multi-Generational Family Company Leading to a Dynasty Fortune. Wealth creation through growth of a single company, Luxottica. Company is the identity of business family. Strategically and selectively diversifying dynasty fortune.

Click the graphic to enlarge
Bill Gates: Company Value Leading to a Multi-Company Family Fortune. Wealth creation though a growth of a single company, Microsoft. Diversification of holdings and assets. Establishment of strategic wealth thought.

Click the graphic to enlarge
Wang Jianlin: Diversified Entrepreneurships Leading to Family Fortune. Wealth creation through network of holdings growth. Increased concentration of holdings in key companies and assets. Strategic diversification across asset classes and geographies.

“The difference between a business family and a business dynasty is the strategy. Everything must be in line with strategy. Selling assets, exiting ventures… followed by reinvestment of capital – in everything strategy sets the rules.” - Baron Albert Frère, Founder and Chairman of Groupe Bruxelles Lambert, one of the largest family enterprises.

Statistics & Graphics: Courtesy of Financial Strategist Board.


_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Friday, September 18, 2015

Redmount’s brief opinion on the Federal Reserve’s (Fed) decision to not move on rates

We think it probably won’t do anything good for markets
  • Attention will now simply shift to “will they/won’t they” for their October meeting.
  • There had been expectations for a “one and done” increase of 0.25%, but that became more and more unlikely given the market tabulations.
  • That said, an increase to the fed funds rate of 0.25% would be a rational response to the probably very slow profile of rate rises over the next 12 to 18 months.
  • Initial rate rises have typically been followed by continued equity market performance on average while the final ones usually brought economic contraction and earnings recessions resulting in stock market losses.
  • And that’s what we’re concerned about, earnings trends. As history suggests, “don’t be afraid of the first interest rate rise, be afraid of the last one
  •  In general, we remain concerned with market volatilities.

Wednesday, September 9, 2015

4 Investment Risks Warren Buffett Says You Should Not Take

What does risk mean to you...and Warren Buffett? 

If you ask the average person, they’re likely to say the probability of losing money. If you ask most financial professionals, they’ll probably equate risk with volatility of returns. (While these may sound similar, they’re not exactly the same thing.) For example.

Let’s say investment A loses 3% one year and gains 2% the next and investment B gains 5% one year and 20% the next. Most people would call investment A riskier since it lost money while financial professionals would say investment B is riskier because the returns were more variable.) But if you ask Warren Buffett, the second richest American and widely considered the greatest investor alive today, he would say they're both wrong.

In his 2014 annual letter to shareholders, Buffett wrote:
“Volatility is far from synonymous with risk… If the investor…fears price volatility, erroneously viewing it as a measure of risk, he may, ironically, end up doing some very risky things.”
Instead of volatility, Buffett measures risk as the loss of purchasing power or basically how much you can actually buy with that money, which is the whole point of actually having it.

______________________________________
What is your risk tolerance?
How much risk is there in your portfolio? 
Start below or Learn more here >>


So what are those “very risky” things investors may do by focusing on volatility? Here are 4 that Buffett mentions and what you should do instead:

1) Keeping long term money in cash.

Many people keep most or even all of the long term money in cash because they're afraid of market volatility. Buffett admits that “owning equities for a day or a week or a year is far riskier (in both nominal and purchasing-power terms) than leaving funds in cash-equivalents,” but he argues that over the long term, “a diversified equity portfolio, bought over time, will prove far less risky than dollar-based securities.” That’s because in the long run, the erosion of the value of your money due to inflation is much more devastating that the short term fluctuations in the stock market.

Average money-market rates are less than a tenth of a percentage point while the average inflation rate last year was 1.6%. That means, the real value of your cash is decreasing by about 1.5% a year. In the short run, that’s a lot less than what you could lose in stocks but in 10 years, your money will have lost almost a quarter of its purchasing power. Compare that to the S&P 500, a selection of 500 of the largest companies in the US, which more than doubled with dividends reinvested over the last 10 years despite the financial crisis in 2008,

Bottom Line: Match your investments to your time frame.

2) Not being adequately diversified.

Another mistake is people having too much in one stock. Often its their employer's stock or the stock received in exchange of a sold company. Sometimes it’s a majority or even all of their money in one stock. There are lots of different reasons. They may know and trust their employer and don’t understand or trust their other options. This stock may have been performing particularly well. The employer stock may be one option out of several in their retirement plan and by spreading their money around, they may inadvertently put too much in their employer stock. They may have acquired the stock as a gift or inheritance or from options, grants, or an employee stock purchase plan and they don’t know what to do with it.

Regardless of the reason, any individual stock (no matter how good the company) is inherently very risky. Unlike what Buffett calls a “diversified equity portfolio” an individual stock can go to zero and never come back. That’s not volatility. That’s a permanent loss of purchasing power.

Bottom Line: Make sure you own a larger number of individual stocks in a a variety of industries or stick to broad-based mutual funds or ETFs that diversify the money for you.

3) Attempting to “time” the market.

Although not thought often as such, this is one of the most common investor mistakes. How many times have you heard people say that they know the market will decline and are waiting until then to jump in. Yes, it’s true that the market will decline at some point. The problem is that no one knows when. 

As Buffett puts it,
“Anything can happen anytime in markets. And no advisor, economist, or TV commentator – and definitely not Charlie nor I – can tell you when chaos will occur. Market forecasters will fill your ear but will never fill your wallet.”
Bottom Line: Instead of trying to time the market (which even Warren Buffett doesn't try to do), make sure you have adequate time IN the market, as that is what matters most. 

4) Active trading.

Instead of trying to time the market, others try to beat it by trading stocks they believe will outperform the market as a whole. This belief can be strengthened if an investor has one or more lucky trades. In many of these situations, the investor mistakes a rising market for his or her investing prowess.

However, many economists believe that the stock market is essentially efficient, which means that it’s extremely difficult if not virtually impossible to beat over the long run. Even if you don’t subscribe to this theory, it’s noteworthy that the vast majority of professional mutual fund managers consistently under-perform the market. Even the few that do outperform over a given time period are actually less likely than average to do so over the next same time period. In other words, any out-performance may be due to luck, exactly what the economists would have predicted.

So if not higher performance, what does all this trading produce? One study found that all this trading costs the average mutual fund about 1.44% per year. That loss comes out of your pocket but is not included in any of the fees reported by mutual funds.

Bottom Line: If professional investment managers, many from top business schools, with access to cutting-edge research and teams of research analysts working for them are unable to consistently beat the market, what makes you think you can? Instead of actively trying to beat the market, limit your trading to making sure your portfolio matches your time frame and risk tolerance, harvest tax losses to offset taxable gains, or switch from higher cost funds to lower cost funds.


_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Tuesday, September 1, 2015

Bond portfolio risk and reward equilibrium

Most bond investors want income to be high and stable. We think a bond portfolio can be built to strike a balance between both—provided investors are willing to take some risk to do it.

Risk, of course, is the price everyone must pay to achieve returns. But one of the more surprising findings in a study, which surveyed more than 2,000 investors and advisors around the world, was the number of people who seemed to be looking for the investment holy grail: high returns and growth with little or no risk.

When one asks investors about their income expectations, one is told investors want to earn at least 6% per year. But when asked about their priorities, three-quarters of investors surveyed put “growth opportunities” and “principal protection” at the top of their lists. “Amount of income,” cited by 71% of investors as a high priority, was a close third.

There’s nothing remarkable about people wanting the highest possible returns from their portfolios—especially when low interest rates have left investors around the world starved for income. We also understand why those who survived recent crises and gut-wrenching market swings want to minimize risk and preserve the wealth they already have.

But it’s hard to achieve both of these objectives consistently. That’s especially true in the current low-interest-rate environment. Allocations to low-risk assets, such as government bonds and cash, aren’t likely to deliver the level of income investors told us they expect from their portfolios. To generate a sizable income distribution from their portfolios, investors have to take risk.

Diversify with a Multi-Sector Approach

Of course, that doesn’t mean investors should blindly reach for the highest-yielding bonds available. In recent years, we’ve seen investors charge into high-yield securities where the compensation wasn’t always commensurate with the risk—think some CCC-rated junk bonds and parts of the leveraged-loan market.

What’s more, following the crowd into the same credit sectors is dangerous. As we’ve seen, yield-hungry investors have been crowding into—and out of—certain sectors with alarming frequency.

A better approach, in our view, is to embrace a multi-sector strategy that diversifies across sectors, geographies and credit quality. Investors who avoid concentrating their allocations in single-sector funds—high-yield, emerging markets, and so on—can instead allocate to high-income asset classes based on where they or their managers see specific opportunities. This makes it possible to capitalize on undervalued bonds no matter what sector they’re in—and it keeps investors from getting trampled by the crowds when they decide to sell.

Broadening the opportunity set in this way can reduce overall risk and potentially increase risk-adjusted returns. Of course, even a highly-diversified strategy won’t erase risk altogether. The reality is that in today’s low-rate environment, investors must take some calculated risks to earn income from their portfolios that’s as high and stable as possible.

_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Tuesday, August 18, 2015

Unlocking resources through better corporate cash management

Companies call on the full resources of their cash management, as they need to grow, execute CapEx or acquisitions.

But going an extra step gives financial managers a chance to help benefit their organization in a less-than-usual way.

The financial manager has an excellent opportunity to contribute strategically to a company's growth, by demonstrating how working capital can be leveraged to serve as a financing and risk management tool in conjunction with, or in addition to, traditional funding methods. This can help strengthen the capital plan and help improve the debt structure.

The benefits of freeing up cash to grow a company:

Reduced financing requirements
  • Existing cash is typically the cheapest form of financing. Using it to finance growth, including for CapEx or acquisitions, can reduce the external financing expense of stock or bond issuance. 
  • The cash released from
    working capital in this instance, should be valued at a weighted average cost of capital (WACC) or, alternatively, the cost of financing the growth should be included in the capital plan typically developed by the financial management team. 
  • In the example above, established working capital standards, can guide a company to release a sizable amount of cash, which applied at a well structured WACC can generate benefit for the company.


Look out for financial ratios and credit ratings
  • Credit rating agencies like D&B review company balance sheets. 
  • Rating agencies usually look upon increases in free cash flow as a positive factor during this process; however, it’s important to note that agencies may penalize companies that ineffectively manage their working capital compared to their peers.
A positive impact on company strength and valuation
  • When looking at a discounted cash flow valuation, the release of working capital that can be achieved by the company would translate as an increase in cash, ultimately improving the valuation of the company.
  • This needs to be looked at carefully and conservatively to ensure that all improvements can indeed be achieved; the finance team is in a prime position to evaluate this.
  • When using weighted average cost of capital, including working capital release in the calculation may boost a company's financials through a one-off increase in free cash flow.
  • Although working capital is priced into a corporate acquisition, the full potential of the synergies often go unrealized when the treasury team, which handles working capital daily, isn’t involved early in negotiations.
  • Working capital is often looked at with more detail in private equity deals, as it is the goal of financial sponsors to maximize asset allocation and drive quick shareholder returns.
More funds for growth
  • Cash unlocked from working capital may help a company grow more quickly, facilitating integration and reducing the execution risk from a cash flow requirement perspective.
  • Strategic events such as mergers, acquisitions, sales, reorganization, etc. provide the perfect opportunity to review the working capital position of the company. 
  • Although the review of working capital and improved management of cash may require some efforts, (improve processes, deploy new banking solutions, and change policies), uncovering these funds can sometimes can release sizable cash to the company's balance sheet.

Released cash can add up quickly

Even a one-day improvement in working capital management parameters can have a profound impact and the finance management leadership plays an important role in this.

Working capital release techniques could be bank-led solutions such as factoring, supply chain finance and card solution, or internal re-engineering such as supplier and customer payment terms standardization. A centralized liquidity structure automated at an in-house bank level can also move the needle in terms of the funding mix of long-term versus short-term debt structures.

As another internal example, larger companies execute ‘payment runs’ on a weekly or fortnightly basis. As these payment files usually are designed to have all payments processed on that same day, the company often ends up paying invoices earlier than their due date (invoices due in the following
week or two) to avoid the cost of executing daily payment runs. Changing this process so that payments are ‘warehoused’ at the bank level until the invoice due date can be a quick and easy way to release working capital, often resulting in a three-day extension of Days Payables Outstanding.

The example above illustrates how the finance manager’s knowledge of the organization’s cash flow can help establish what the achievable extension of company's days payable outstanding is, and therefore, what the subsequent reduction in the cash conversion cycle would be.

Best practices to consider
  • Involve finance staff as often as possible in to decision-making process.
  • In M&A situations finance team can propose the use of cash from working capital as a funding option.
  • Identify the focus areas for working capital release.
  • Prioritize the deployment of processes and policies, which can quickly release cash from the working capital to accelerate the funding growth.
  • Centralize treasury operations: consider using shared service centers to standardize payments flows and leverage funding from an in-house bank with automated cash concentration structures.
  • Hand off functions to banks, such as the financing of some of the strategic suppliers through a supply chain finance program, or the management of some local processes (such as payment file translations).

Note: Calculations of Working Capital used for the examples in this document follow the bellow formulas:

Days Payable Outstanding [DPO] = (Trade Accounts Payable / Cost of Goods Sold) * 365
Days Receivable Outstanding [DSO] = (Trade Accounts Receivable / Revenue) *365
Days Inventory Outstanding [DIO] = (Inventory / Revenue) * 365
Cash Conversion Cycle [CCC] = DSO – DPO + DIO

_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Thursday, August 13, 2015

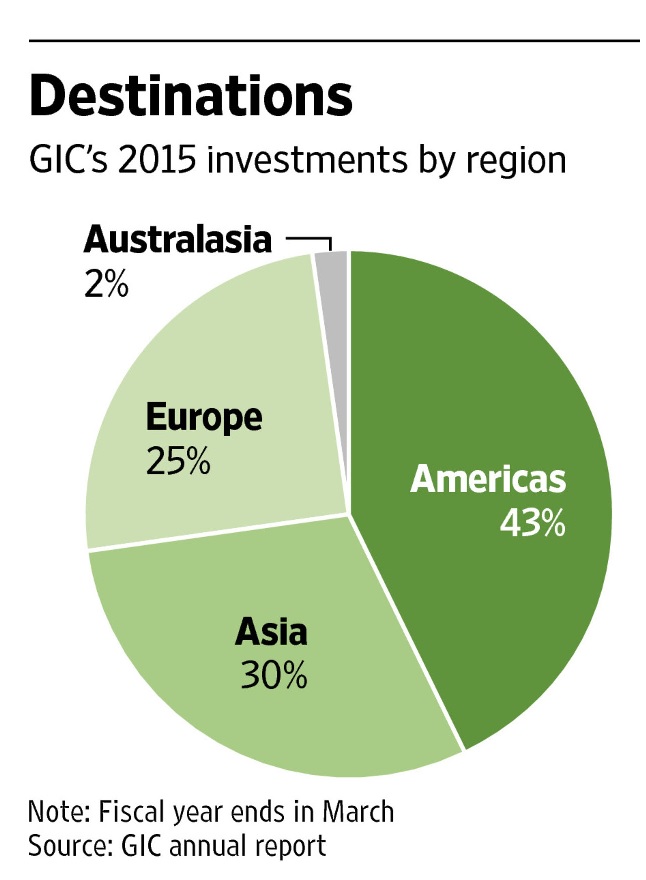
Singapore’s sovereign-wealth fund has warned that it expects lower returns over the next five to ten years

Singapore’s sovereign-wealth fund, one of the world’s biggest and most sophisticated investors, has warned that it expects lower returns over the next five to ten years because global economic growth and earnings don’t look promising.

GIC Pte Ltd., whose largest investments are in North America, said ultralow interest rates have inflated asset prices in developed markets. It said opportunities remained in developed and emerging markets, although it cut its exposure to Europe during Q12015.

“The fall in interest rates to historic lows in most advanced economies has caused prices of a broad range of asset classes to rise,” Lim Chow Kiat, GIC’s group president and chief investment officer, said in the fund’s annual report for the fiscal year that ended in March. “The sharp rise of asset prices, when the global economy is still struggling to gain a firm foothold, makes the investment environment particularly uncertain and unpredictable.”

Even China, which has faced waves of heavy selling in stocks in the past month, remains a long-term investment destination for the fund, GIC said. The fund said it still has a positive view on the economy and believed in the ability of the government to carry out overhauls. Recent volatility is ”fallout of rampant market speculation,” Mr. Lim said.

“China in the last three years has demonstrated its seriousness to reforms and we believe that the country’s future is good," he said.

GIC publishes its annual report following a lengthy audit process. The sovereign-wealth fund is a major global player, and its investments are closely watched. The fund said its investments globally gave it a 4.9% 20-year real rate of return for the fiscal year that ended March 31, or a 6.1% return over the same period in U.S. dollar terms.

_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Monday, August 3, 2015

Global Economic Environment at the Half-year Mark of 2015

US
Starting with the US economy, which began the year on the wrong foot, we believe the weakness of the first quarter is temporary in nature, mostly due to exceptional factors. US GDP is reported to have contracted by 0.2% in Q1, though there could be revisions to this estimate. The pace of activity was held back by harsh winter conditions, disruptions to ports on the West Coast, reduced energy investment following the decline in oil prices (which subtracted about 0.5 percentage points from Q1 growth), and weaker exports held back by a stronger dollar. Moreover, seasonal adjustment techniques in the official statistics have resulted in Q1 growth systematically reported as much lower than the full-year average.

Both oil prices and the dollar have stabilized; as a consequence, the supply adjustment in energy markets has decelerated: The number of rigs in operation continues to decline but at a much slower pace, and the drag on exports (equivalent to about 0.6 percentage points for every 10% real appreciation) should have largely run its course. Meanwhile, the labor market continues to improve, with new job creation in the non-farm sector running at a 3-month average of about 200,000; the unemployment rate has declined to 5.3%, close to the Congressional Budget Office’s estimate of the non-accelerating inflation rate of unemployment (NAIRU). 

A tighter labor market has begun to exert pressure on wages. The Employment Cost Index accelerated to 2.6% year-over-year in Q1, the highest pace since 2008; wages and salaries were up 5.0% year-over-year in May. Core inflation has remained stable at close to 1.5%; the base effects from lower oil prices will begin to fade by August, and the recent pickup in oil prices will then gradually push headline inflation closer to core; wage pressures are then likely to translate into more significant price increases over the remainder of the year and into 2016. 

Overall, these data make us confident that the US recovery remains on track. This in turn should lead the Fed to hike interest rates later this year, most likely in late Q3 or in Q4. Financial markets have begun to anticipate the likely move, with 10-year Treasury bond yields rising from about 1.64% at the end of January to about 2.35% by the end of June. Markets are, however, pricing a slower pace of monetary policy tightening than the Fed itself has indicated. While the central bank will likely start tightening at a slow pace, it might need to move faster once inflation pressures build up; this would imply an even larger disconnect from current market expectations. 

Europe
Eurozone growth has surprised on the upside in Q1, as we had predicted in our previous Global Macro Shifts publication. At +0.4%, Q1 marked the 8th consecutive quarter of positive quarterover-quarter (qoq) growth. The pickup in economic activity has been spurred, most importantly, by a weaker euro, which has boosted the competitiveness of eurozone exporters. QE by the European Central Bank (ECB) also helped, by reducing funding costs and pushing more liquidity into the banking system. Recent indicators suggest that positive momentum persists: Purchasing manufacturers index, retail sales and lending indicators all remain on an uptrend. 

Though most of the eurozone has seen a broad-based pickup in activity, the sustainability of this varies across countries. Spain, for example, has been outperforming on the back of its reforms and the efforts made to put public finances on a sounder footing. Germany maintains strong international competitiveness, currently buttressed by a healthier domestic demand. Germany’s trade surplus runs at about 7% of GDP, proof of its enduring export prowess. In France and Italy, however, the acceleration seems more cyclical in nature; both countries need a more determined reform effort to accelerate growth on a more sustainable basis. 

The recently launched QE program has successfully begun inverting the previous contraction of the ECB’s balance sheet, which shrank by as much as one third from its peak. Together with existing programs for the purchase of covered bonds and ABS,1 QE has boosted the central bank’s balance sheet by about €200 billion (bn), compared to a target of about €1.1 trillion (tn) as of June 30. Some analysts and market players have speculated that the ECB might abandon its QE program in the near future, given the stronger-than-expected pace of growth. ECB President Mario Draghi, however, has repeatedly emphasized that the bank intends to carry out its program at least until September 2016, and that in any event it would need convincing evidence that inflation is converging to its 2% target in a sustainable way before considering a policy change. 

The Greek saga remains the main cloud on the horizon of the European recovery. Greek voters rejected the latest creditors’ proposal in a referendum held on July 5. The referendum asked voters to either accept or reject the latest economic program that resulted from six months of difficult negotiations with the European Union, ECB and International Monetary Fund (IMF). Eurozone leaders had warned that a “no” vote would most likely result in Greece exiting the eurozone. While negotiations are expected to resume, the risk of “Grexit” has substantially increased. Rather than predicting the outcome of these discussions, we prefer to focus on the possible consequences of the worst-case scenario. Should Greece leave the euro, we believe this would cause a temporary shock to financial markets, with peripheral spreads widening in the eurozone, and a spike in global risk aversion. We are also confident that the eurozone’s current firewalls are strong enough to limit contagion, so that the adverse impact should be limited and temporary in scope. 

Japan 
Japan appears to be finally succeeding in its struggle against deflation. Core CPI is running at about 2%, even subtracting the impact of tax hikes. Even the collapse in oil prices has not been enough to push the country back into deflation, and nominal GDP growth remains on a healthy uptrend. Japan’s success in keeping inflation in positive territory is especially remarkable given the extremely adverse external environment, where many countries have experienced deflationary pressures. This constitutes very encouraging evidence that the “first arrow” of Abenomics, namely a much more decisive QE push, has proved effective. 

The positive impact of Abenomics can be seen on output growth: GDP expanded faster than expected in Q1, at over a 2% qoq seasonally adjusted annualized rate. Inventory accumulation played an important role, but there were also encouraging signs of a rebound in both private consumption and capital expenditures. Moreover, output prices have been running significantly above input prices, indicating that profitability will likely improve, which would support the outlook for a further pickup in investment. Last year’s tax hike, therefore, has not stopped the recovery, contrary to what a number of analysts feared, especially given that a tax hike derailed Japan’s attempt to exit deflation in 1997. This tax hike, the cornerstone of the fiscal strategy, therefore, was a calculated but courageous gamble—and has paid off. This should be considered as another major success of the government’s policy: The “second arrow,” a prudent fiscal policy, promotes confidence in long-term debt sustainability. 

The “third arrow,” structural reforms, remains the most important part of the equation—and has been the focus of most questions and skepticism since the launch of Abenomics. In this area, some important progress has already been made. On the financial side, the portfolio rebalancing of the Government Pension Investment Fund has begun spilling over to other institutions, such as Japan Post and the public employees’ pension funds. Probably more important are efforts to strengthen corporate governance through improving transparency and encouraging a more active role by shareholders and corporate boards. 

Japan’s productivity, after running at about 3% in the 1980s and about 2% in the 1990s, now languishes at a mere 1%. Weak corporate management practices and the ensuing inefficiencies are the main culprits for this productivity slowdown. Japan must boost nominal GDP growth on a durable basis to guarantee the sustainability of its massive debt burden. Besides a permanent rise in the inflation rate, this requires stronger overall real GDP growth. This must be achieved in the face of intensifying demographic pressures, as Japan’s population will continue to age rapidly in the coming decades. Government programs to boost the labor force, in particular by raising female participation, can help, but will not fully offset the impact of aging. To achieve stronger real GDP growth therefore, Japan must achieve faster productivity growth, importantly requiring a strengthening of corporate governance. Japan has therefore adopted a new corporate governance code, which formalizes explicit responsibilities for corporate boards to scrutinize management and communicate information to shareholders, and requires every board to have at least two external directors. Much more work will be needed to increase flexibility and boost productivity, but the measures already taken confirm that the government realizes that it must attempt to tackle the toughest reforms, even if this means clashing with powerful vested interests.

_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.

Monday, July 27, 2015

US Leading Indicator

RATE-OF-CHANGE TICKS UP, CONFIRMING MARCH 2015 LOW


The US Leading Indicator for June is up 5.5% from one year ago, with the 1/12 rate-of-change holding steady from its upward revised May value. Several successive months of strengthening building permits and a steepening yield curve have pushed the Index higher. The March 1/12 low confirms our expectation for a cyclical low for US Industrial Production in early 2016.


_____________________________________________
Clicking the Like button on various social media platforms, such as LinkedIn, Facebook, etc. does not constitute a testimonial for or endorsement of Redmount Capital Partners LLC or any Investment Advisor Representative. “Like” is not meant in the traditional sense. Posts must refrain from recommending investment advisory services or providing testimonials for our firm, since they are strictly prohibited. Please understand that we are required to delete such posts, since this is a regulatory requirement.